
Unraveling the Four Returns of Turnkey Rental Properties
By Scott A. Stanfield
Real estate is often lauded for its consistent, multipronged returns. Turnkey rental properties are no exception, providing investors with an enticing blend of passive income and growth potential. For the unfamiliar, let’s break down the financial rewards these investments offer.
Understanding the Four Returns
When discussing turnkey rental investments, there are four principal avenues of profit:
1. Cash Flow
2. Loan Pay Down
3. Appreciation
4. Depreciation (Tax Savings)
While at a glance it might seem unusual to divide property returns into these distinct categories, the logic becomes clear once you realize the impact each has on purchasing decisions, reserve funds, market evaluations, and the ever-important tax implications.
1. Cash Flow: The Realized Monthly Gain
Cash flow represents the monthly income after covering all operational costs, including the mortgage. Simplified, it’s:
Cash Flow = Sum Revenue – Sum Expenses
For turnkey single-family rentals, the initial cash flow generally gives a return on investment (ROI) between 5% and 15%. A leveraged position, i.e., purchasing the property with a mortgage, will result in a higher ROI from cash flow. Cash flow tends to grow over time because rental rates typically increase faster than the expenses.
2. Loan Pay Down: A Steady Path to Increased Equity
Every mortgage payment is a combination of interest (the lender’s profit) and principal (reduction of your outstanding loan).
Mortgage Payment = Principal + Interest
This principal portion, which grows slightly with every payment, is the loan paydown. It increases your property’s equity – the difference between the property’s value and what you owe.
Equity = Value – Owed
Though this equity builds monthly, converting it to cash requires additional steps like selling or refinancing.
For an example, imagine that you have a mortgage payment that is $550 per month. If your mortgage balance owed is $100,000 at a 5 % annual interest then the first month’s interest is $416, leaving $134 of your $550 payment to reduce the principal. Over time, as the principal decreases, a larger chunk of your payment goes towards it.
5%/12 = 0.42% interest per month
$100,000 x 0.42% = $416
$550 – $416 = $134
3. Appreciation: The Potential Powerhouse of Returns
Appreciation is the increase in your property’s value over time. The U.S. historical average appreciation rate for single-family homes lies between 3.5% and 3.8%. In different locations around the country homes will increase in value more than the historical average. Finding these locations requires research, speculation, and higher risk levels. Not only is this speculatory in nature, but properties with high appreciation potential often cost more which will cause you to have a lower or even negative cash flow. Speculate right and the potential gains from appreciation are tantalizing. To get a feel for how appreciation can leverage your ROI, simply divide the purchase price of the property by your down payment, which we will refer to as “the lever”, and then multiply this ratio (the lever) by the historical appreciation rate. The equation is given below:
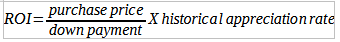
To illustrate, let’s assume you are purchasing a property for $100,000 and the loan-to-value ratio is 80%, then the borrowed balance from the lender is $80,000:
80% x $100,000 = $80,000
The corresponding down payment is $20,000:
$100,000 – $80,000 = $20,000
Your leverage is given by dividing the purchase price by the down payment which, for this example, gives 5:
$100,000 / $20,000 = 5
Your leveraged ROI for a 3.5% appreciation rate is then 17.5%:
5 x 3.5% = 17.5%
The 17.5% ROI is, in my opinion, impressive and highlights the power of leverage and appreciation. In reality, the 17.5% will be a little lower because of closing costs. Furthermore, the 17.5% is the performance after year 1 but will underestimate later years. The reason is because appreciation is a compounding financial instrument!
Does this matter? Absolutely, compound returns are powerful. Your return from appreciation will increase rapidly and reward you for holding onto the property. Your effective leveraged ROI after five and ten years of ownership are 18.8% and 20.5%, respectively.
What does this equate to in dollars for the $100,000 example from above? An additional $1,268.63 after 5-years and an additional $6,059.88 after 10-years.
4. Depreciation: The Silent Tax Saver
Though not a direct earner, depreciation is a mighty tool for tax savings. For taxes, businesses are allowed to deduct the assets they purchase. For low-cost, expendable items, the deduction occurs in one year. For assets that last a long time, such as a property, the deductions occur incrementally each year. For single-family rentals, the IRS allows depreciation over 27.5 years. This doesn’t account for the land value, only the building. Reducing taxable income through depreciation can significantly bolster your end-of-year financial standing.
To illustrate the power, let’s assume the taxable income from your property without including depreciation is $5,000. Let’s further assume your profit is taxed at 24%. Depreciation can reduce your tax rate of 24% to an effective tax rate below 10%. It is even possible to achieve 0% and still produce a profit. Without depreciation you would pay $1,200 in taxes (0.24 x $5,000) instead you will pay around $500 or less.
5. Putting it All together: The Total Return
The total ROI is the sum of the ROI for cash flow, loan paydown, and appreciation. For the first year of ownership, the total ROI for the single-family homes I target for my business is around 7% from cash flow, 6% from loan paydown, and 17.5% for appreciation for a total annual return of 30.5%. The effective tax rate is around or below 5%.
So, how good is a 25% to 30% annual return? The average annual return for some of the greatest investors of all time are listed below to help provide a reference:
• Warren Buffet: 22%
• Peter Lynch: 29.2% from 1977 to 1990
• George Soros: 30% or more
The annual return from the turnkey rental investment is on the order of the performance achieved by some of the more recognized investor greats.
Conclusion: Harnessing the Quartet of Returns
Turnkey rental properties offer an intricate web of financial rewards: monthly cash flow, equity growth via loan paydown, potential appreciation, and tax benefits through depreciation. Understanding each facet can fine-tune your investment strategy, ensuring you’re not only earning but also optimizing every dollar.
Optimizing your return requires a well-honed plan that is based on market generated data, predictive financial models, and commonsense. Executing the plan efficiently, i.e., minimizing the hours spent working, requires systems for the different business processes. Developing or acquiring this level of detail is justified because the annualized returns are substantial.
To learn more, visit my website www.scottastanfield.com
If you have a topic that you would like to be covered or any questions, you can also reach me at scott@scottastanfield.com.
Thanks for reading.